Non-profit Association Audits
Independent assurance for organisations built on trust.
Community organisations run on the confidence of their members, their funders and their volunteers. An independent audit is one of the ways that confidence is maintained — an outside review of the financial records, carried out by someone with no involvement in preparing them.
- Audits of non-profit associations and trust accounts
- Conducted by an auditor with decades of public practice experience
- A process explained clearly to committees and volunteers
An independent look at the numbers.
An audit is an independent examination of an organisation's financial records and reporting. The auditor is not involved in preparing the accounts; the whole value of the exercise lies in that separation. The result is an opinion that members, funders and regulators can rely on because it did not come from inside the organisation.
Many incorporated associations and community organisations are required to have their accounts audited — under their own rules, under the terms of a grant, or under the legislation they are incorporated beneath. Others choose to, simply because it is good practice when you are looking after money on behalf of other people.
Bachmann Robinson conducts audits of non-profit associations and trust accounts. We understand that most committees are made up of volunteers rather than accountants, so we explain what we need, why we need it, and what our findings mean — without making the process any more daunting than it has to be.
It usually depends on your organisation's rules, its size, and the terms of any funding it receives. Have your constitution or rules to hand when you call and we can talk it through.
Why independent assurance matters.
Non-profit organisations hold money that belongs, in a real sense, to their members and their community. Committee members change, treasurers hand over, and volunteers come and go. An annual independent review is what keeps that continuity honest.
It also protects the people doing the work. A treasurer who has done everything correctly deserves to have that confirmed by someone outside the organisation, and an incoming committee deserves to know the position it is inheriting.
- Members can see that funds have been accounted for
- Funders and grant bodies receive the assurance they ask for
- Committees and treasurers have their work independently reviewed
- Governance and record-keeping tend to improve year on year
What we can help you with
The work we are most often asked to carry out for associations and organisations.
Non-profit association audits
Independent audits of the annual financial records of incorporated associations, clubs and community organisations.
Trust account audits
Audits of trust accounts, where an organisation or business is required to have money held on behalf of others independently examined.
Reviewing financial records
Examining the accounting records, bank records and supporting documentation for the period under audit.
Documentation and governance
Looking at how decisions, approvals and receipts are documented, and where the organisation's processes could be tightened.
Audit preparation guidance
Telling you in advance what will be required, so a volunteer treasurer is not caught out at the last minute.
Final reporting
Providing the audit report for the organisation's annual reporting, and explaining what it says to those who need to understand it.
The audits we accept depend on the organisation and the requirements that apply to it. Give us a call with your rules or funding conditions to hand and we can confirm what is involved.
Trust account audits.
Where money is held on behalf of other people, there is usually an obligation to keep it in a separate trust account and to have that account independently audited. The requirements come from the legislation or licensing regime the business or organisation operates under, and they can be quite specific about timing and scope.
We conduct trust account audits alongside our association audit work. If you are unsure whether an audit is required in your case, or what period it needs to cover, get in touch and we can work through the obligations that apply to you.
Our audit process
Structured, predictable, and explained as we go — particularly for committees doing this for the first time.
- 01
Understand the organisation
We look at your rules or constitution, the requirements that apply to you, and how the organisation's finances are actually run.
- 02
Agree the scope and timing
We confirm what the audit covers, the period involved, and the timetable — including when you need the report for your annual meeting.
- 03
Request the records
We provide a clear list of what we need: financial records, bank records, minutes, and the documentation supporting the year's transactions.
- 04
Conduct the audit
We carry out the examination independently, raising queries with the treasurer or committee as they come up rather than saving them to the end.
- 05
Report our findings
We issue the audit report and talk the committee through what it says, including any matters worth attending to before next year.
As auditors we remain independent of the organisation and of the preparation of its accounts. Independence is what makes the report worth having.
Experience that goes back a long way.
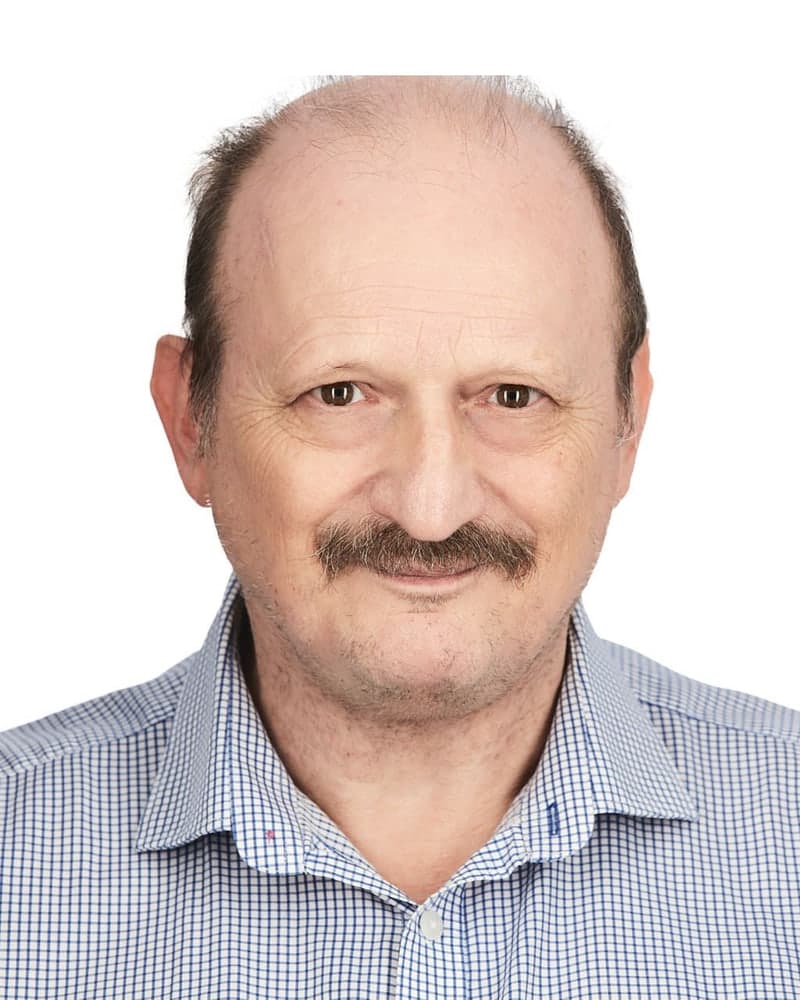
Richard Dinsdale conducts our audits of non-profit associations and trust accounts. He has been with the firm since October 1996 and in public accounting since 1975, alongside an extensive range of accounting and taxation clients.
Before joining Bachmann Robinson he spent twelve years with a Brisbane second-tier firm and ten years with a Brisbane litigation accountant, developing deep experience in valuations and investigations. For the last eighteen years he has helped organise the local IPA/CPA discussion group, which meets monthly.
Who this service is for
Incorporated associations
Associations required to have their annual financial records audited under their rules or the legislation they are incorporated beneath.
Community organisations
Local groups accounting to their members and their community for the money they hold.
Clubs
Sporting, social and recreational clubs whose committees need an independent review before the annual general meeting.
Not-for-profit organisations
Organisations whose funding or governance arrangements call for independent assurance over their accounts.
Organisations receiving grant funding
Where the terms of a grant require audited financial information to be provided to the funding body.
Businesses holding trust accounts
Where money is held on behalf of others and the applicable regime requires the trust account to be audited.
Preparing for your audit
A little preparation makes the process considerably shorter, and it is all work the organisation should be doing anyway.
Have the records complete
Bank statements, receipts, invoices and the accounting records for the whole period, rather than the parts that were easy to find.
Keep minutes and approvals together
Committee minutes recording approvals, appointments and significant decisions are part of the picture, not an afterthought.
Know your deadlines
Annual general meetings, reporting obligations and funding deadlines all have dates attached. Tell us early so the timetable works.
Independence has limits
Because we act as auditor, there is work we cannot do for the same organisation. We will be clear about where that line sits.
This information is general in nature. Audit and reporting requirements depend on your organisation's rules, its size, its funding arrangements and the legislation that applies to it. Speak with our team for advice relevant to your situation.
Useful regulator resources
Published by Australian and Queensland government bodies. Which of these applies depends on how your organisation is set up and funded.
These are external government resources, published and maintained by their respective agencies rather than by Bachmann Robinson. Links do not imply a recommendation of their content. For anything specific to your circumstances, speak with our team.
You may also be interested in
Common questions about audits
Does our association actually need an audit?
What is the difference between an audit and having the accounts prepared?
What will you need from us?
Our treasurer is a volunteer. Is that a problem?
When should we book the audit in?
Can you also do our bookkeeping or prepare the accounts?
We advise on your systems. Our IT partner builds them.
Websites, social media, AI and automation for growing businesses — at a preferred rate for Bachmann Robinson clients. The first conversation is free.

Let’s talk about what you need.
Whether you have a straightforward question or a more complex financial situation, our team is here to help.
Level 1, 265 Brisbane St, Ipswich QLD · Mon–Fri, 9am–5pm